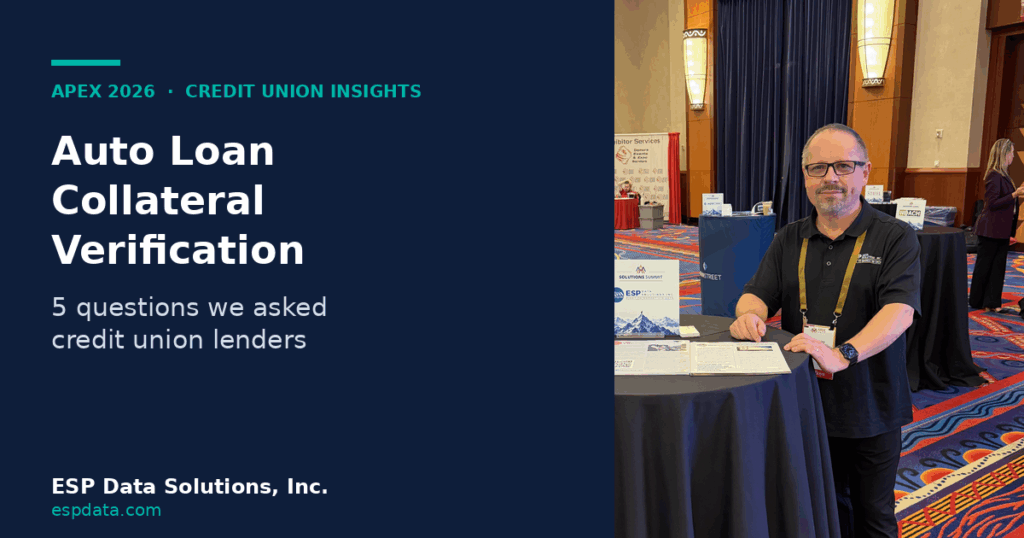
Auto loan collateral verification is only as good as the vehicle data behind it. On October 14, 2026, ESP Data Solutions CEO Greg Skoczylas joined credit union leaders from Connecticut, Delaware, Massachusetts, New Hampshire, and Rhode Island at APEX 2026, the Cooperative Credit Union Association’s annual conference at Mohegan Sun in Uncasville, Connecticut.
At the ESP table in the Solutions Summit exhibit area, Greg asked lending teams five questions about how vehicle information moves through their auto loan process. Here are those questions, why each one matters, and what a credit union can do with the answers.
What is auto loan collateral verification? It is the process of confirming a vehicle’s identifying attributes and comparing them with the application, supporting documents, and valuation inputs before funding.
Why Vehicle Data Was a Fitting Topic at APEX 2026
Fraud and lending technology were both on the APEX 2026 agenda, with sessions on the evolving fraud landscape, a “Scam Lab” simulation, and automated lending. Vehicle data sits right where those two topics meet.
The numbers explain why. Point Predictive’s 2026 Auto Lending Fraud Trends Report estimates that auto lending fraud exposure reached a record $10.4 billion in 2025, up from $9.2 billion the prior year. One category stands out for collateral: powerbooking, where a vehicle’s description is inflated with features or options it doesn’t have so the loan can exceed the car’s real value. Digital Dealer’s coverage of the report attributes about $750 million of that exposure to powerbooking and collateral fraud, a 19% year-over-year increase.
The vehicle record is not the collateral itself. However, it helps the lender identify and evaluate the vehicle securing the loan.
Question 1: How Does Vehicle Information Get Into Your Lending System Today?
Every auto loan file needs a vehicle description: year, make, model, and usually more. That data can arrive several ways:
- From the dealer through an indirect lending platform
- From the member on an online or branch application
- From a loan officer who types it in from a buyer’s order or title
- From a VIN decode performed automatically by the loan origination system (LOS)
Each path introduces different error and verification risks. Dealer-supplied descriptions, for example, are one point where inaccurate or inflated vehicle information can enter an indirect lending workflow. As a result, the first step in auto loan collateral verification is simply knowing which source your file relies on.
Question 2: When a VIN Comes Into Your System, Where Does the Vehicle Data Come From?
Many lending systems decode VINs already. Even so, it’s worth confirming which data source sits behind that decode, how often it’s updated, and how far back its coverage goes.
That matters because a VIN provides a more standardized reference than a free-text vehicle description. A decode based on manufacturer-submitted data helps lenders compare the reported vehicle with the attributes associated with that VIN. For instance, VinLiNK™ draws its Basic report on documents manufacturers provide to federal regulators, covers model years 1981 and newer, and returns structured XML or JSON that can be consumed through an LOS integration.
What VIN Decoding Can and Cannot Verify
- Can return: Model year, make, model, body style, engine, and other manufacturer-reported attributes associated with the VIN.
- Can help flag: Differences between those decoded attributes and the vehicle described on the application or buyer’s order.
- Can add context: Original MSRP and manufacturer specifications, depending on the report level.
- Cannot confirm on its own: That the VIN belongs to the physical vehicle presented for financing, or the vehicle’s ownership, title status, mileage, or condition.
- Cannot establish: Every factory or dealer-installed option, or the vehicle’s current market value.
Question 3: Do Your Loan Officers Ever Have to Manually Enter Year, Make, Model, or Trim?
This was the question that drew the most consistent answer at APEX 2026. In Greg’s informal conversations at the event, representatives from several smaller credit unions said their staff still enter at least some vehicle data manually. This was a qualitative observation from the conference, not a representative industry survey.
Manual entry adds a step to every file and creates more chances for small errors. If an incorrect model year or trim is used in the valuation, it can affect the vehicle value used in the loan-to-value (LTV) calculation. Meanwhile, a typo can lead to failed or incorrect system matching, or require extra manual review.
If loan officers are still typing vehicle details, the cause may be a missing VIN decode integration, a decode that doesn’t return enough detail, or simply a long-standing process habit. Automating that step reduces rekeying and gives each file a more consistent starting record.
Question 4: What Happens When the VIN Comes Back Incomplete or the Trim Doesn’t Match?
This question goes straight to collateral risk. A mismatch can result from a data-entry error, an incorrect VIN, incomplete manufacturer data, or differences between the reported and decoded configuration. Because powerbooking also produces mismatches, each one deserves a closer look.
A sound workflow treats a mismatch as a signal, not a verdict:
- Flag it automatically when decoded year, make, model, or engine differs from the application
- Route it for review instead of letting it pass silently into underwriting
- Ask for documentation, such as the window sticker or build sheet, when trim or options drive the valuation
- Track mismatches by dealer so recurring exceptions can be reviewed alongside other vendor-performance signals
NCUA’s indirect lending due diligence guidance calls for effective controls and ongoing monitoring of indirect lending relationships. It also identifies inflated or fraudulent trade-in or purchase prices as dealer-management red flags.
Common Mismatches and What to Do Next
- Model year differs: This may reflect a typo, an incorrect VIN, or confusion between the model year and calendar year. Compare the VIN and model year against the title, buyer’s order, and other available documentation, then resolve the discrepancy according to your institution’s verification procedures.
- Make or model differs: Could be a wrong VIN on the application or a VIN from another vehicle. Follow your institution’s verification procedures. A VIN plate photo, title, or other supporting documentation may help resolve the discrepancy, but no single document should be treated as conclusive on its own.
- Trim or engine differs: The application may contain an incorrect description or list a higher trim than the decoded result. Request the window sticker or build sheet and recheck the LTV according to your institution’s exception procedures.
- Decode returns incomplete data: Some fields depend on what the manufacturer reported. Request supporting documentation and route the file for manual review rather than filling gaps by hand.
VIN decoding helps identify differences between reported and decoded attributes. It does not by itself confirm that the VIN belongs to the physical vehicle presented for financing, so it works best alongside documentation and, where needed, physical inspection.
Question 5: Do You Need MSRP, Specifications, or Valuation-Related Data for Underwriting?
Underwriting often needs more than year, make, and model. Original MSRP can provide historical pricing context, while weights, dimensions, and technical specifications can help confirm the vehicle configuration. Warranty information can provide additional manufacturer context. None of these fields establishes current market value or replaces an appropriate valuation source.
VinLiNK™’s Basic Plus report adds deeper vehicle details, including MSRP, weights and dimensions, and warranty information. In addition, the Enhanced report draws on other manufacturer technical documents. Together, they give underwriters a manufacturer-based reference to compare against the application and the valuation.
Putting Auto Loan Collateral Verification Into Practice
Taken together, Greg’s five questions describe a simple checklist for any credit union lending team:
- Know your vehicle data source for every loan channel.
- Decode the VIN automatically at application, not after funding.
- Remove manual entry of year, make, model, and trim wherever possible.
- Flag and review mismatches between the decoded VIN and the reported vehicle.
- Add manufacturer specifications and MSRP where underwriting needs them.
For credit unions that want to review an existing portfolio, batch VIN decoding can process up to 250,000 VINs at once. That makes it possible to compare decoded attributes with historical loan records when a lender investigates a recurring mismatch pattern. For related reading, see our articles on credit union auto loans and OBBBA and floorplan lending fraud.
Frequently Asked Questions
Can VIN decoding help detect powerbooking?
Yes, as one layer. Decoding the VIN gives you manufacturer-based year, make, model, and other core attributes to compare against the dealer’s description. Because a VIN doesn’t encode every factory option, pair it with documentation such as a window sticker when options drive the loan amount.
Can VinLiNK™ integrate with our loan origination system?
Yes. VinLiNK™ is a web API that returns structured XML or JSON, so credit unions and their technology partners can connect it to loan origination, dealer, and underwriting systems. The integration effort depends on your LOS, so it’s best to review it with your LOS provider or IT team.
Does VinLiNK™ provide MSRP?
Yes. The Basic Plus report includes MSRP along with weights and dimensions and warranty details.
Is VIN decoding the same as a vehicle valuation?
VIN decoding describes the vehicle’s manufacturer-reported attributes. A valuation estimates current market value based on mileage, condition, and market data. The two are complementary: the decode describes what the vehicle is, and the valuation estimates what it’s worth.
What did ESP Data Solutions do at APEX 2026?
ESP Data Solutions CEO Greg Skoczylas attended APEX 2026 at Mohegan Sun on October 14, 2026, and met with credit union lending and leadership teams at the ESP table in the Solutions Summit area. A recurring theme in those informal conversations was that several smaller credit unions still enter at least some vehicle data manually.
Talk to Us About Your Lending Workflow
If any of these five questions sparked a “we’re not sure” in your lending team, that’s a good place to start. Contact ESP Data Solutions to see how VinLiNK™ can bring structured, manufacturer-reported vehicle data into your auto loan collateral verification process, whether we met at APEX 2026 or not.